


That is why this story should not be reduced to: Cameroon is borrowing FCFA 250 billion. The deeper questions are: Who borrows? Who owns? Who captures the return? Who assumes the risk? And who exits with the value? Financial sovereignty cannot be measured on the day a government buys a bank. It must be measured when the entire lifecycle of ownership is complete.
By Ali Dan Ismael, Editor-in-chief The Independentist News
As Amazon associate this site earns from qualifying purchases
Get books on productive Sovereignty and statecraft by Martin Mungwa from Amazon
Cameroon bought control of one of its largest commercial banks in May and described the transaction as a major step toward strengthening national financial sovereignty.
Four months later, the state is reportedly preparing to borrow FCFA 250 billion—approximately €381 million—from local banks, with Ecobank arranging the financing. According to Africa Intelligence, part of the transaction is intended to refinance the state’s acquisition of the former Société Générale Cameroun, now renamed General Bank of Cameroon, even as the authorities consider a possible future sale.
That is more than a banking story. It raises a fundamental question about what financial sovereignty actually means. Is sovereignty achieved when the state acquires a bank? When it controls the shares? When it can protect depositors during the departure of a foreign shareholder? Or must financial sovereignty ultimately be judged by a harder test: Who pays? Who borrows? Who owns? Who controls the capital? Who captures the return? And who exits with the value? Those questions should now be asked.
From Société Générale Cameroun to General Bank of Cameroon
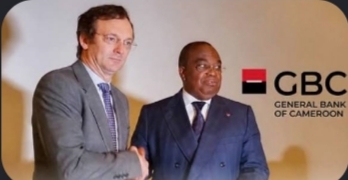
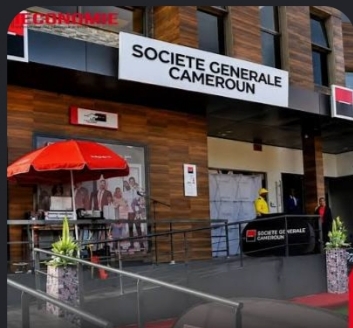
The government’s intervention did not begin in September. On May 12, 2026, Cameroon completed its acquisition of the 58.08 percent stake previously owned by France’s Société Générale. Because the state already held 25.60 percent, the transaction increased public ownership to 83.68 percent of the bank. The remaining 16.32 percent is held by SanlamAllianz Cameroun Assurances. The acquisition price was reported at FCFA 129 billion, including taxes.
The government renamed the institution General Bank of Cameroon, or GBC. The Ministry of Finance presented the transaction in explicitly strategic terms. It described the acquisition as strengthening Cameroon’s financial sovereignty, protecting national interests, preserving continuity of banking services, securing deposits, and helping establish a modern, competitive and inclusive national banking system capable of supporting structural transformation. Those are legitimate objectives.
When the controlling foreign shareholder of a major domestic bank decides to leave, the state cannot necessarily behave like a passive spectator. Depositors matter. Employees matter. Corporate borrowers matter. Payment relationships matter. Banking confidence matters. An unmanaged exit could create disruption. The government therefore had a plausible public-policy reason to intervene. But acquiring the bank was only the first transaction. The more important question is what happens next.
The FCFA 250 Billion Question
On September 9, Africa Intelligence reported that Yaoundé hopes to raise FCFA 250 billion from local banks by mid-October, with Ecobank arranging the financing. The publication says the operation is intended, in particular, to refinance the state’s acquisition of Société Générale Cameroun, while the authorities examine a possible future sale. The wordings matter.
It does not establish that the entire FCFA 250 billion is being borrowed solely to reimburse the FCFA 129 billion acquisition price. “In particular” it suggests that the financing may have broader purposes. Until the structure is publicly explained, it would be irresponsible to assume what accounts for the difference. But the difference makes disclosure even more important.
What portion of the FCFA 250 billion refinances the acquisition? What does the balance finance? Is part of it intended for recapitalization? Does it cover other state obligations? What is the maturity? What is the interest rate? What fees are being paid? What guarantees have been offered? Is repayment bullet, amortizing or otherwise structured? Are there covenants affecting future ownership? And if the bank is eventually resold, must some or all of the financing be repaid immediately?
These are not questions for financial specialists alone. They determine the real public cost of ownership. The Purchase Price Is Not the Cost of the Investment When governments announce acquisitions, public discussion often focuses on the acquisition price. But purchase price and total economic cost are not the same thing. Cameroon’s reported FCFA 129 billion payment purchased Société Générale’s 58.08 percent stake.
That establishes an acquisition price. It does not establish the lifecycle cost of the state’s intervention. There may also be financing costs, transaction expenses, technology-transition costs, capital requirements, restructuring costs and future expenditures necessary to prepare the institution for a new ownership structure. Indeed, less than a month after the takeover, GBC shareholders were called to consider a capital increase. The bank’s existing share capital was reported at FCFA 12.5 billion, while the new CEMAC regulatory minimum for banks is FCFA 25 billion.
That does not establish that the Cameroonian state alone will finance the capital increase. But it illustrates why an acquisition cannot be evaluated by looking only at the cheque written on closing day. The proper calculation is conceptually closer to this: Acquisition cost, financing cost, recapitalization, transition and restructuring costs, additional public risk assumed − dividends received, − eventual sale proceeds = real economic outcome for the public. That calculation cannot yet be completed. But somebody in government should already be making it.
Financial Sovereignty Must Survive the Lifecycle Test
The phrase financial sovereignty is attractive. But sovereignty cannot be measured at the moment of acquisition alone. Suppose the state intervenes, protects deposits, keeps the institution functioning, reorganizes its management, strengthens its capital and ultimately sells the bank to a strong strategic investor at a price that compensates the public for the capital and risk it assumed. That could represent successful transitional state intervention.
Now consider the opposite possibility. The state pays FCFA 129 billion for the controlling stake, assumes additional financing, bears borrowing costs, provides new capital, carries transition risk, and eventually sells the institution without recovering the full economic cost borne by the public. Legal ownership would have existed. But was lasting financial sovereignty created?
That is why the most important question may ultimately be: Who exits—and at what price? If the government regards its ownership as transitional, the exit strategy deserves as much scrutiny as the acquisition. Who will be permitted to buy? Will Cameroonian private capital participate? Will pension funds participate? Will employees have an ownership opportunity? Will another foreign banking group simply replace Société Générale? Will shares eventually be listed publicly? Will the state retain a strategic minority stake? Will there be one controlling buyer or diversified ownership? And how will the bank be valued at exit?
Those questions determine whether the transaction ultimately broadens domestic productive ownership or simply transfers control from one owner to another after the state absorbs the transition cost.
Domestic Borrowing Creates Another Question
The proposed financing introduces a particularly interesting dimension. According to Africa Intelligence, the state intends to raise the FCFA 250 billion from local banks. There is nothing inherently improper about sovereign borrowing from domestic banks. Governments around the world borrow from their domestic financial systems. But Cameroon is not operating in an environment of unlimited capital.
The African Development Bank reports that domestic financial development remains relatively weak: credit to the economy was only 17.5 percent of GDP in 2025. It also reports shrinking liquidity in the regional financial market and emphasizes Cameroon’s substantial development-financing needs. That makes the allocation question important.
If local banks lend FCFA 250 billion to the government, what is the opportunity cost? Would part of that capital otherwise have financed manufacturers? Farmers? SMEs?Housing?Infrastructure? Export businesses? Technology companies? The answer cannot simply be assumed. Government borrowing does not automatically crowd out private investment, and a stronger banking institution could itself contribute to productive lending.
But the question should be measured. Does this transaction increase the productive capacity of Cameroon’s financial system by more than the capital it absorbs from that system? That is the test. There Is an Interesting Circularity The structure also contains a financial circularity worth examining. The state acquired a commercial bank. The state is now reportedly preparing to borrow from commercial banks partly to refinance that acquisition.
In other words, the banking system may help finance the government’s ownership of one of the banking system’s own institutions. Again, that is not inherently problematic. The issue is the terms. If the state refinances a short-term or expensive acquisition obligation with a well-priced, longer-term facility, that may be sensible treasury management.
If the new financing creates expensive sovereign obligations without an adequate return from the acquired asset, the assessment changes. We cannot determine which is true without the financing terms. That is precisely why those terms matter. GBC Should Not Be Portrayed as a Failed Bank There is another point requiring discipline.
The government’s acquisition should not automatically be interpreted as the rescue of an insolvent bank. Published figures do not establish that General Bank of Cameroon is a failed financial institution. Recent reporting based on the bank’s accounts placed its balance sheet at approximately FCFA 1.4 trillion, with more than FCFA 1 trillion in customer resources and substantial customer financing.
The African Development Bank has raised broader concerns about Cameroon’s increasing public-sector role in banking and the fiscal and governance risks associated with state recapitalizations and acquisitions. But that is not the same thing as an audit conclusion that GBC itself is insolvent.That distinction matters.
A serious analysis should not manufacture financial distress simply to make the government’s decision look worse. The stronger question is whether state ownership is the best long-term structure for a viable commercial bank and whether the eventual transition creates or destroys public value. Why Did Société Générale Want Out? There is another question beyond Cameroon. Société Générale had owned and operated the institution for decades.
Its decision to leave was part of the French banking group’s broader retreat from several African markets. That means the Cameroonian state was responding to a strategic decision made elsewhere. This is one of the realities of foreign ownership. Foreign capital can enter. Foreign capital can also decide to leave. The host country then inherits choices it did not initiate. Should another foreign buyer immediately take over? Should domestic investors be assembled? Should the state intervene? Should the institution be broken up? Should ownership be broadened through capital markets? Cameroon chose state intervention.
The important question now is whether the intervention becomes a bridge toward stronger domestic financial capacity or a permanent fiscal obligation. The AfDB Warning Should Be Taken Seriously This question is particularly important because GBC does not exist in isolation from Cameroon’s broader public-finance environment.
The African Development Bank’s 2026 Cameroon Country Report identifies continuing weaknesses in public financial management, including the absence of a single Treasury account, non-publication of financial statements by public enterprises, and delays in implementing public investment projects. Those observations do not prove that the GBC transaction is badly managed. But they make transparency more important.
A state expanding its role in banking while simultaneously facing public-finance governance weaknesses should voluntarily provide more information, not less. The public should be able to understand the acquisition structure, refinancing terms, capitalization plan, governance model and intended exit strategy.
Financial sovereignty without financial transparency is incomplete sovereignty. Who Owns Is Only the Beginning This is where the General Bank story enters a larger debate about productive sovereignty. Ownership matters. But ownership alone is insufficient. A state can own a bank that does little to finance productive enterprise. A foreign-owned bank can sometimes finance an economy efficiently.
A domestically owned bank can allocate capital poorly. A publicly owned bank can become either a powerful development institution or an expensive vehicle for political lending. The question is therefore not merely: Who owns the shares? It is: What does ownership cause the institution to do differently?
Will GBC increase financing for productive Cameroonian businesses? Will it finance manufacturing? Agriculture? Housing? Infrastructure? Export-oriented firms? Professional enterprises? Technology? Will credit allocation be commercially disciplined? Will politically connected borrowers receive preferential access? Will bad loans eventually migrate to the taxpayer? Who appoints the board? What qualifications determine management appointments? What protections exist against political interference? These questions define the difference between public ownership and productive ownership.
A Bank Is a Capital-Circulation System A bank is not merely a building containing deposits. It is part of a country’s circulation system for capital. Households deposit savings. Businesses require working capital. Entrepreneurs require investment. Homebuyers require mortgages. Governments borrow. Investors require payment systems. Trade requires letters of credit and foreign exchange. The bank sits between accumulated capital and productive use. That makes banking sovereignty fundamentally different from simply owning shares in a bank.
Real financial sovereignty means having institutions capable of mobilizing domestic savings and directing capital toward productive activity while preserving depositor confidence, controlling risk and earning sustainable returns. If public ownership achieves that, it can be strategically valuable. If public ownership instead converts scarce national savings into politically allocated credit, recurring recapitalization and eventual public losses, the flag on the share certificate will not rescue the economic result.
The Mungwa Questions Applied to GBC
The General Bank transaction therefore deserves to be tested through the same questions that should govern any major public asset. Who signs? Who is legally committing Cameroon to the FCFA 250 billion financing? Who pays? What public entity services the debt, from what revenues, and at what interest cost? Who owns? What will the state’s 83.68 percent shareholding look like after recapitalization and eventual investor entry? Who controls? Who appoints management and determines credit policy while the state remains dominant? Who supplies the capital? Which domestic banks participate in the financing, and what concentration of exposure results? Who captures recurring value? Who receives dividends, interest, fees and eventual capital gains? And finally: Who exits?
If the government sells, who becomes the next controlling shareholder—and what does Cameroon retain after the transaction is complete? That last question deserves to be asked before the next transaction, not after it. Temporary Ownership Can Be Good Policy. There is nothing inherently contradictory about nationalizing or acquiring an asset temporarily and then selling it. Governments have done so successfully during financial crises.
The public sector can act as a bridge when markets are unable to produce an orderly transition. The measure of success is not permanent state ownership. The measure is whether state intervention preserves value and ultimately leaves the productive system stronger.

If Cameroon protects GBC’s depositors, preserves a major domestic bank, strengthens its governance, modernizes its systems, expands productive lending and eventually introduces strong domestic or strategic investors at a favorable valuation, history may judge the intervention well. But if the state assumes the acquisition cost, financing cost, recapitalization burden and commercial risk only to sell the bank later under terms that socialize the cost and privatize the upside, the judgment will be very different. That is why the exit must be designed now. This Is the Real Meaning of Financial Sovereignty
Financial sovereignty should not mean that government owns everything. Nor should it mean that foreign ownership is automatically suspect. Sovereignty is the capacity to make choices without being captured by any single external or domestic actor. It is the ability to preserve essential institutions when a foreign shareholder exits. It is the capacity to negotiate financing intelligently. It is the institutional discipline to protect deposits without politicizing credit. It is the ability to attract external capital without surrendering control over national development priorities. And it is the capacity to know when state ownership has accomplished its purpose and when it should end. That is mature financial statecraft.
A Different Kind of Cameroon Story
The recent SONARA and Olembé disputes raise questions about the cost of contractual decisions after they go wrong. The General Bank story is different. This is a decision still in motion. The borrowing has reportedly not yet been completed. The refinancing terms are not yet publicly known. The future ownership structure has not yet been settled. That makes this story more than an autopsy.
It is an opportunity for scrutiny before the lifecycle is complete. Cameroon does not have to wait seven years for a court judgment or arbitration award to ask the hard questions. They can be asked now. What exactly is being refinanced? What does FCFA 250 billion buy the state? What is the cost of the money? What additional capital will GBC require? What is the ownership strategy? What return does the state expect? What is the timetable for strategic investors? How will an eventual sale be valued? And what will remain in Cameroon after the state exits?
The Final Test
The government called its acquisition of Société Générale Cameroun an assertion of financial sovereignty. That claim should not be dismissed. But neither should it simply be accepted because the state now owns 83.68 percent of the shares. The verdict will come later. It will depend upon whether public capital was protected. Whether the bank grew stronger. Whether depositors remained secure. Whether productive enterprises gained access to capital. Whether political interference was contained. Whether financing costs were controlled. Whether taxpayers received value for the risk they assumed. And, if the state eventually sells, whether Cameroon exits the transaction with more national financial capability than it possessed when Société Générale decided to leave.
That is why this story should not be reduced to: Cameroon is borrowing FCFA 250 billion. The deeper questions are: Who borrows? Who owns? Who captures the return? Who assumes the risk? And who exits with the value? Financial sovereignty cannot be measured on the day a government buys a bank. It must be measured when the entire lifecycle of ownership is complete.
As Amazon associate this site earns from qualifying purchases
Get books on productive Sovereignty and statecraft by Martin Mungwa from Amazon
https://www.amazon.com/s?k=Book+by+Martin+mungwa&i=specialty-aps&srs=121082092011&crid=31ZNM3LO2LYZ&sprefix=book+by+martin+mungwa%2Cspecialty-aps%2C356&linkCode=ll2&tag=njokings-20&linkId=53ef1d93f2626b23f8a7580230cf12c6&language=en_US&ref_=as_li_ss_tl
Ali Dan Ismael, Editor-in-chief The Independentist News